The $618K Moment: How Europe Blew Up My Retirement Math
It started, as many questionable ideas do, with a glass of red wine and an internet connection.
It was spring 2025. I was somewhere between my second and third glass when I typed what felt like a perfectly reasonable search query: cheap European cities to live in, in countries with a tax treaty with Canada and with access to cultural events.
As you do…
The results came back: Portugal, Spain, Bulgaria, Greece. Portugal and Spain kept coming up — and for good reason. But I wanted to dig deeper into some less obvious options first. So I kept scrolling.
Bulgaria stopped me cold.
I don’t know exactly what I expected. But what I found was a country with a flat 10% income tax rate, a tax treaty with Canada, and a cost of living that made my Edmonton brain short-circuit.
Two cities jumped out immediately — Sofia, the capital, buzzing and underrated. And Plovdiv, with its bohemian Old Town, its Kapana art district, cobblestone streets and café culture that looked like something out of a dream I didn’t know I was having.
I thought: I could live like a hippie in Europe. And retire years earlier than 65.
The red wine may have helped that thought along.
Step 1: Build a Budget
I did what any newly-obsessed person does at midnight — I built a budget. Not a rough estimate. A proper budget. With categories. With euro-to-Canadian-dollar conversions. With a travel fund calculated to four significant figures.
I called it the Firebird Lean+.
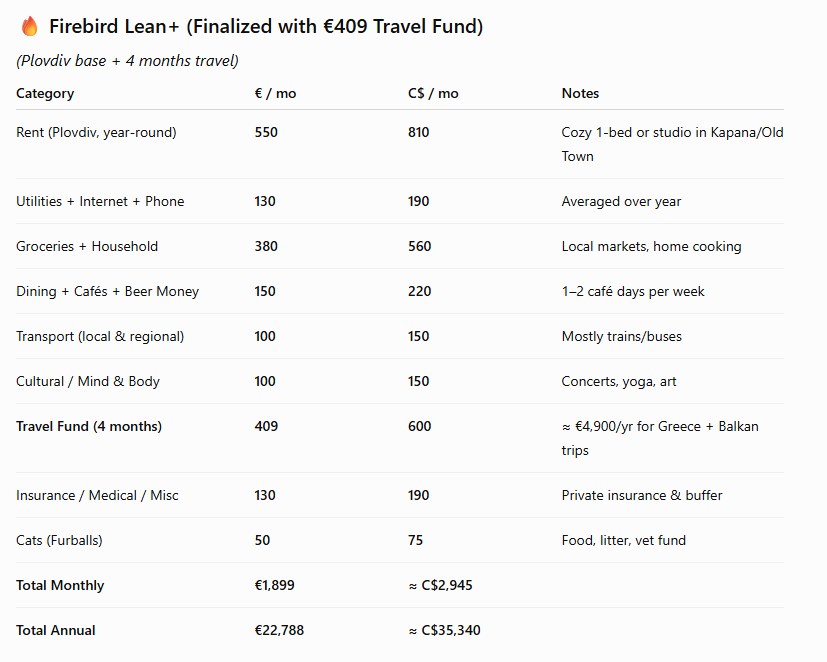
C$35,340 a year. Cats included.
And just to be clear — that travel fund isn’t a wish. It’s four months of actual travel across Europe, built right into the budget, while keeping a real home base in Bulgaria. The cats stay. The apartment stays. You just… also go to Greece sometimes…
At the time, my thinking was laser focused: how lean can I actually live? How much earlier could I retire if I stripped everything back to what actually matters? Concerts. Coffee. Local markets. The occasional beer. My cats. A train ticket to Greece every few months.
It felt not just possible, it felt exciting!
Step 2: Build Four Scenarios
But I didn’t stop there. Because once you start pulling on that thread, you can’t stop.
One budget wasn’t enough. I needed to know what different versions of this life would actually cost. So I built four:
Plan A — Plovdiv Core: Rooted, artsy, lowest cost. Ten months in Plovdiv, two months of travel.
Plan B — Sofia Cultural: More urban, metro access, richer arts scene, slightly higher rent.
Plan C — Greek Nomad: Coastal and mountain balance, Thessaloniki base, island retreats.
Plan D — Firebird Hybrid: Eight months Plovdiv, two months Greece, two months Budapest. Averaged across all three.
| Plan | Style | Monthly (C$) | Annual (C$) |
| A – Plovdiv Core | Rooted, artsy | $3,090 | $37,080 |
| B – Sofia Cultural | Urban, metro | $3,525 | $42,300 |
| C – Greek Nomad | Coastal, travel-rich | $3,970 | $47,640 |
| D – Firebird Hybrid | Balanced, semi-nomadic | $3,605 | $43,260 |
The range across all four plans? €2,100 to €2,700 per month. That’s C$3,090 to C$3,970. For a full life, in beautiful cities, with travel built in.
I stared at those numbers for a long time.
Step 3: Run the Retirement Math
Then I did something that changed everything.
I ran the actual retirement math — how large a portfolio would I need to fund each lifestyle indefinitely, at three different withdrawal rates?
| Plan | Annual Cost (C$) | 4% Portfolio | 5% Portfolio | 6% Portfolio |
| A – Plovdiv Core | $37,080 | $927K | $742K | $618K |
| B – Sofia Cultural | $42,300 | $1.06M | $846K | $705K |
| C – Greek Nomad | $47,640 | $1.19M | $953K | $794K |
| D – Firebird Hybrid | $43,260 | $1.08M | $866K | $721K |
And then I sat back and stared at the screen.
$618,000.
At a 6% withdrawal rate, Plan A — the Plovdiv life, with the cats and the concerts and the four months of travel — required a portfolio of $618,000 CAD.
That number hit differently than anything my financial planner had ever put in front of me. Because the alternative — retiring in Edmonton, in the snow, in the freezing damn cold that lasts six months of the year — was looking like $1.5M or more.
Or.
I could be bohemian. Drinking wine in a small studio apartment with my cats, getting ready for the next arts festival.
And here’s what really got me, the Bulgarian budget wasn’t just cheaper because of lower prices. It was cheaper because entire categories of expenses simply disappear. No car. No car insurance. No condo fees. All these line items that quietly eat my Edmonton paycheque every month, gone. Just – gone.
$618K suddenly felt less like a fantasy and more like a finish line I could actually see.
Step 4: Then It Got Even Better
I should have stopped there. Gone to bed. Let the red wine wear off.
I didn’t.
Because I hadn’t factored in something important yet: I’m Canadian, and Canada has a pension system. A small workplace pension kicking in at 55. CPP and OAS starting at 65.
I’d always thought of those as distant, almost theoretical benefits. Something that would help “someday.” That night, I actually ran the numbers.
| Source | Start Age | Annual (C$) | Notes |
| Small Pension | 55 | $3,270 | Indexed modestly |
| CPP | 65 | ≈$9,000 | Assuming moderate contributions |
| OAS | 65 | ≈$8,500 | Based on residency rules & full eligibility |
| Total Age 65+ | 65 | ≈$17,500–18,000 | ≈$1,500/month pre-tax |
And then I added them into the retirement model.
| Plan | Portfolio at 50 | Lowest Point | Portfolio at 65 | Portfolio at 80-90 | Outcome |
| A — Plovdiv Core | $550K | ~$530K (age 52) | ~$620K | $700-750K | 🟢 Never depletes, grows |
| B — Sofia Cultural | $550K | Gentle decline | Stabilizes | Plateaus | 🟡 Stable |
| C — Greek Nomad | $550K | Drifts to ~$250K | Levels off | Levels off | 🔵 Manageable |
| D — Firebird Hybrid | $550K | Moderate dip | ~$400-450K | Modest growth | 🟣 Safe |
Plan A — the Plovdiv Core — didn’t just survive to age 90.
The portfolio never depletes. It actually grows back toward $700–750K by age 80.
I’m not just not running out of money. I’m ending up with more than I started with.
I sat back from my laptop and just… laughed. Not because it was funny. Because it was real. Because the math kept working no matter which angle I checked it from.
The Part That Surprised Me Most
This budget looks very different from how I think about retirement now. The question has shifted from how little can I survive on to what do I actually need to live well? That’s a different calculation and one I’ll get into in future posts.
But in that spring 2025 rabbit hole, with red wine and a spreadsheet and two cats judging me from the couch?
Lean felt like freedom.
So I did what any reasonable person would do.
I booked a flight.
A note on the numbers: $618K was my starting point — the figure that first made early retirement feel real. The math has evolved since that evening, and you can follow how in future posts. But this is where it all began.
Nothing on this site constitutes financial advice. I’m sharing my own journey — please do your own research and consult a professional before making financial decisions.